20/80 Payment Plans in Dubai: How Post-Handover Payments Affect Your Investment
Understanding Flexible Property Payment Plans
Purchasing property in Dubai involves more than choosing a desirable location or attractive apartment layout. The payment structure can significantly influence affordability, cash flow, and the long-term financial obligations associated with ownership.
A 20/80 payment plan in Dubai is one example of how developers may structure payments across different stages of a residential project.
However, the exact meaning of this arrangement depends on the individual development and its contractual terms.
Understanding when payments become due, how post-handover installments work, and whether rental income can support future obligations is essential before committing to a property purchase.
What Is a 20/80 Payment Plan in Dubai?
A 20/80 payment plan generally divides the property’s purchase price into two portions.
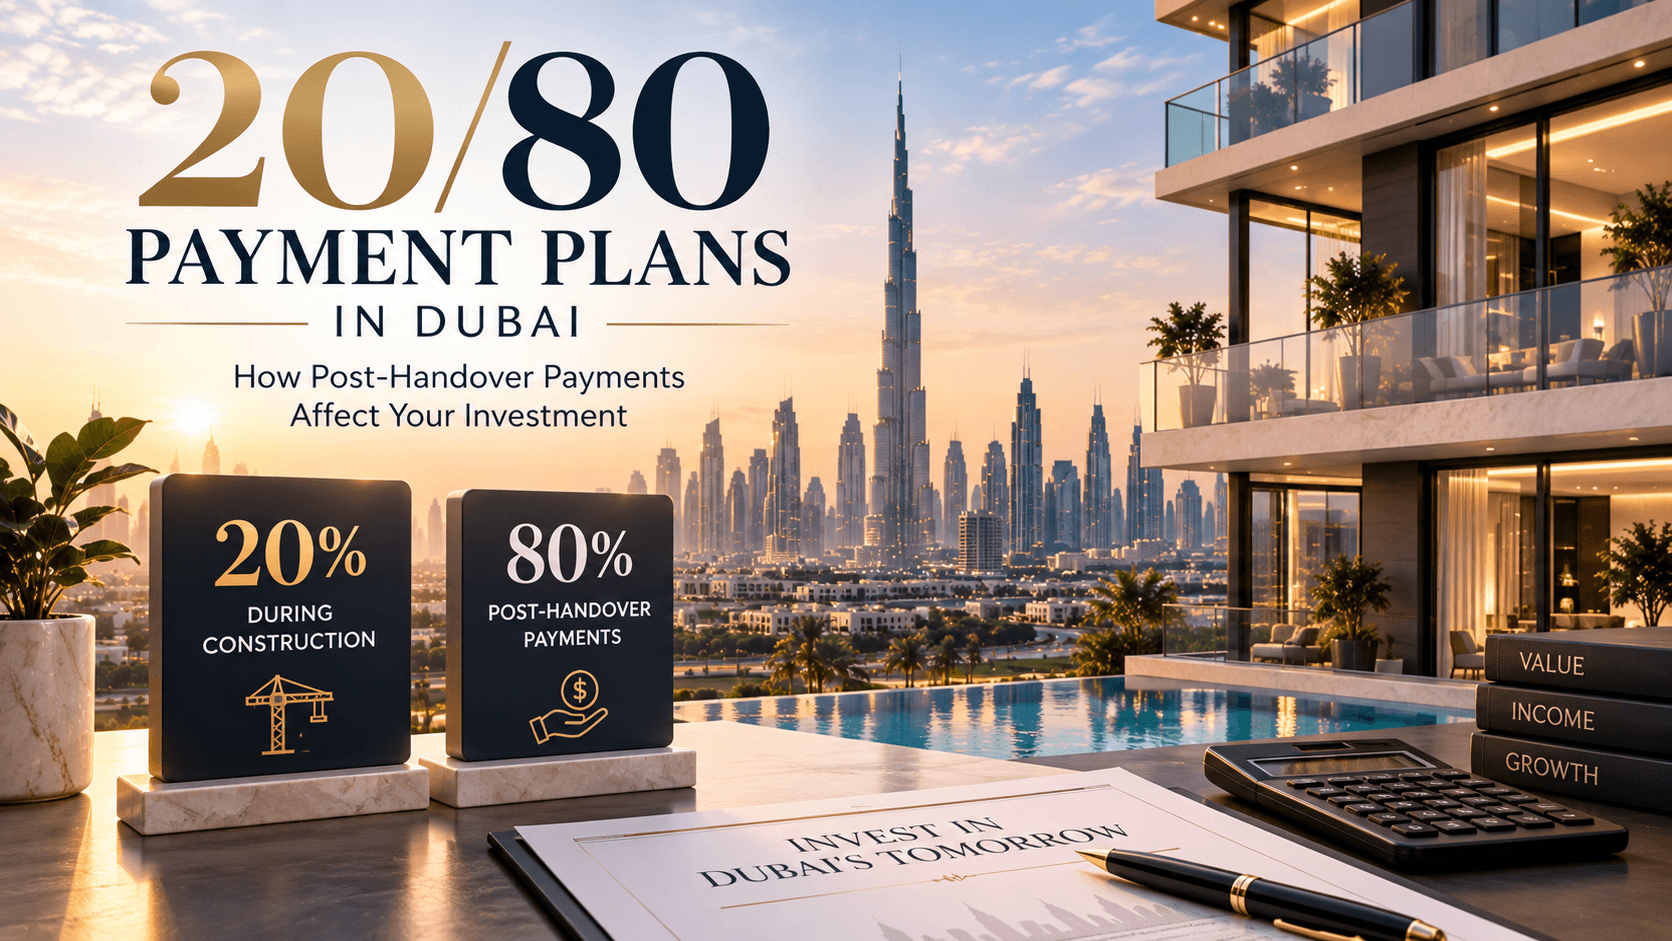
In one common structure, the buyer pays 20% during the initial purchasing or construction period and the remaining 80% at handover.
However, some developers may advertise variations in which part of the outstanding balance is payable through installments after handover.
These arrangements should not be treated as interchangeable.
Buyers must review the actual payment schedule to determine whether the 80% balance is due immediately upon completion, spread over a post-handover period, or divided between several milestones.
The advertised ratio alone does not explain the complete financial commitment.
How Post-Handover Payment Plans Work
A post-handover payment plan allows a buyer to pay part of the purchase price after the property has been formally handed over.
Depending on the agreement, payments may be divided into monthly, quarterly, or other scheduled installments.
This structure can provide buyers with additional time to manage their finances while potentially allowing them to occupy or rent the property.
However, post-handover arrangements differ significantly between developments.
Some contracts may require a large payment at handover before the remaining balance becomes payable over time.
Others may include specific conditions relating to ownership registration, financing, resale, or missed installments.
Understanding these conditions is essential when comparing projects.
A Practical Example of a 20/80 Payment Structure
Consider a hypothetical Dubai apartment priced at AED 1,200,000.
Under a payment structure requiring 20% before handover, the buyer would pay AED 240,000 during the initial period.
The remaining 80% would equal AED 960,000.
If the full balance were due at handover, the buyer would need access to that amount at the required time.
If the developer instead offered a genuine post-handover arrangement over 60 months, the outstanding AED 960,000 would represent AED 16,000 per month, assuming equal installments and no additional financing charges.
This example illustrates why the payment timeline matters as much as the advertised percentage.
Why Payment Flexibility Matters to Property Investors
Property investment requires careful management of available capital.
A buyer who commits a large proportion of their savings to one property may have less flexibility to cover unexpected expenses or pursue other financial opportunities.
Structured payment plans can help distribute the purchase cost over time, but they do not reduce the total property price unless a separate discount is offered.
Investors should distinguish between affordability at the time of booking and the ability to complete every future installment.
A relatively small initial payment can make a property accessible, but the remaining financial obligation may still be substantial.
Can Rental Income Cover Post-Handover Installments?
One potential attraction of post-handover arrangements is the possibility of generating rental income while continuing to pay the developer.
However, rental income should not be assumed to cover the outstanding balance.
Consider a hypothetical apartment generating AED 90,000 in annual gross rent.
That represents AED 7,500 per month before service charges, maintenance, vacancy periods, management fees, and other expenses.
If the buyer’s monthly installment is AED 16,000, rental income alone would not cover the payment obligation.
The investor would need additional funds to meet the difference.
This is why a realistic cash-flow calculation is more useful than relying on an advertised rental yield.
Understanding Gross and Net Rental Yield
Rental yield is commonly used to compare property investment opportunities.
Gross rental yield is calculated by dividing annual rental income by the purchase price and multiplying the result by 100.
For example, an apartment purchased for AED 1,200,000 and rented for AED 90,000 annually would generate a hypothetical gross yield of 7.5%.
However, this figure excludes operating expenses.
Net rental yield provides a more detailed picture by accounting for relevant ownership costs.
Investors should also distinguish rental yield from overall investment return, which may include changes in property value, transaction costs, financing expenses, and eventual resale proceeds.
Why the Handover Date Matters
The handover date influences when the buyer may gain access to the apartment and potentially begin earning rental income.
For a property under construction, the timing of future installments should be evaluated alongside the expected completion schedule.
A payment plan that appears manageable over several years may become more demanding if multiple installments fall due before the apartment can be occupied or leased.
Buyers should also understand whether the payment schedule is linked to calendar dates, construction milestones, handover, or a combination of these factors.
The exact contractual terms determine when the buyer becomes responsible for each payment.
Comparing 20/80 and 40/60 Payment Plans
Different payment structures distribute financial obligations differently.
Under a hypothetical 40/60 arrangement, a buyer would pay 40% before or during construction and the remaining 60% according to the agreed schedule.
A 20/80 arrangement may require less capital initially but leave a larger outstanding balance for a later stage.
Neither structure automatically produces a higher investment return.
The more relevant question is whether the payment schedule aligns with the buyer’s income, savings, financing arrangements, and intended holding period.
A buyer should compare the total purchase cost, installment timing, potential charges, and handover conditions rather than evaluating the initial payment percentage alone.
The Importance of Developer Credibility and Project Registration
Before entering an off-plan agreement, buyers should verify the development’s registration and relevant project information.
Dubai Land Department explains that escrow accounts are used to hold funds collected from purchasers of off-plan units, with the purpose of regulating project development and protecting buyers’ interests.
Buyers should confirm that payment instructions correspond to the registered project and its approved escrow arrangements.
The developer’s previous delivery record, current construction progress, communication practices, and contractual documentation should also be reviewed.
A flexible payment plan is not a substitute for proper due diligence.
How Location Influences Rental Income Potential
Payment flexibility becomes more meaningful when considered alongside the property’s ability to attract residents.
Apartments with convenient access to employment centers, schools, transport connections, healthcare facilities, and lifestyle destinations may appeal to different tenant groups.
However, rental demand can vary considerably between buildings within the same neighborhood.
Investors should compare similar completed apartments and consider factors such as floor area, furnishings, building age, parking, amenities, and service charges.
The expected rental income should be based on realistic comparable properties rather than promotional projections.
Evaluating One By Nine’s Payment Options
Buyers exploring One By Nine can review the project’s residential offering and request its current payment schedule.
The development includes studio, one-bedroom, and two-bedroom apartment configurations within a boutique residential building in Meydan.
When evaluating any payment arrangement for the project, purchasers should confirm the exact booking amount, construction-stage installments, handover payment, and any available post-handover obligations.
The advertised payment structure should always be checked against the latest official sales documentation.
A specific 20/80 arrangement should not be assumed to apply unless it is explicitly offered for the selected unit.
Nine Developments and the Importance of Clear Purchase Information
Nine Developments provides information about its residential development activities and project offering.
For prospective buyers, the developer’s official website is a starting point for reviewing available property information and requesting current sales documentation.
The final purchase decision should be based on verified pricing, apartment specifications, contractual payment obligations, and the buyer’s financial circumstances.
Clear communication about these details helps purchasers understand the complete commitment involved in buying a property.
Common Financial Risks Buyers Should Consider
Post-handover payments can create ongoing financial commitments that continue after the buyer receives the property.
Unexpected maintenance expenses, periods without tenants, changes in rental rates, or personal income fluctuations can affect the ability to meet these obligations.
Buyers should also establish whether the contract permits early settlement, resale before full payment, or mortgage financing.
Any applicable fees or restrictions should be understood before signing.
A financial buffer can help manage unexpected costs, but buyers should avoid assuming that future rental income or property appreciation will automatically resolve affordability concerns.
Conclusion: A Payment Plan Should Support Your Investment Strategy
A 20/80 payment plan can offer a different distribution of purchasing costs, while a genuine post-handover arrangement may allow part of the balance to be paid after the apartment is delivered.
However, the financial value of these arrangements depends on the complete payment schedule rather than the advertised ratio alone.
Buyers should examine the purchase price, installment amounts, handover conditions, rental income potential, ownership costs, and contractual restrictions.
By evaluating these factors together, investors can determine whether a payment structure supports their financial objectives without creating obligations they may struggle to meet.